Study Summary
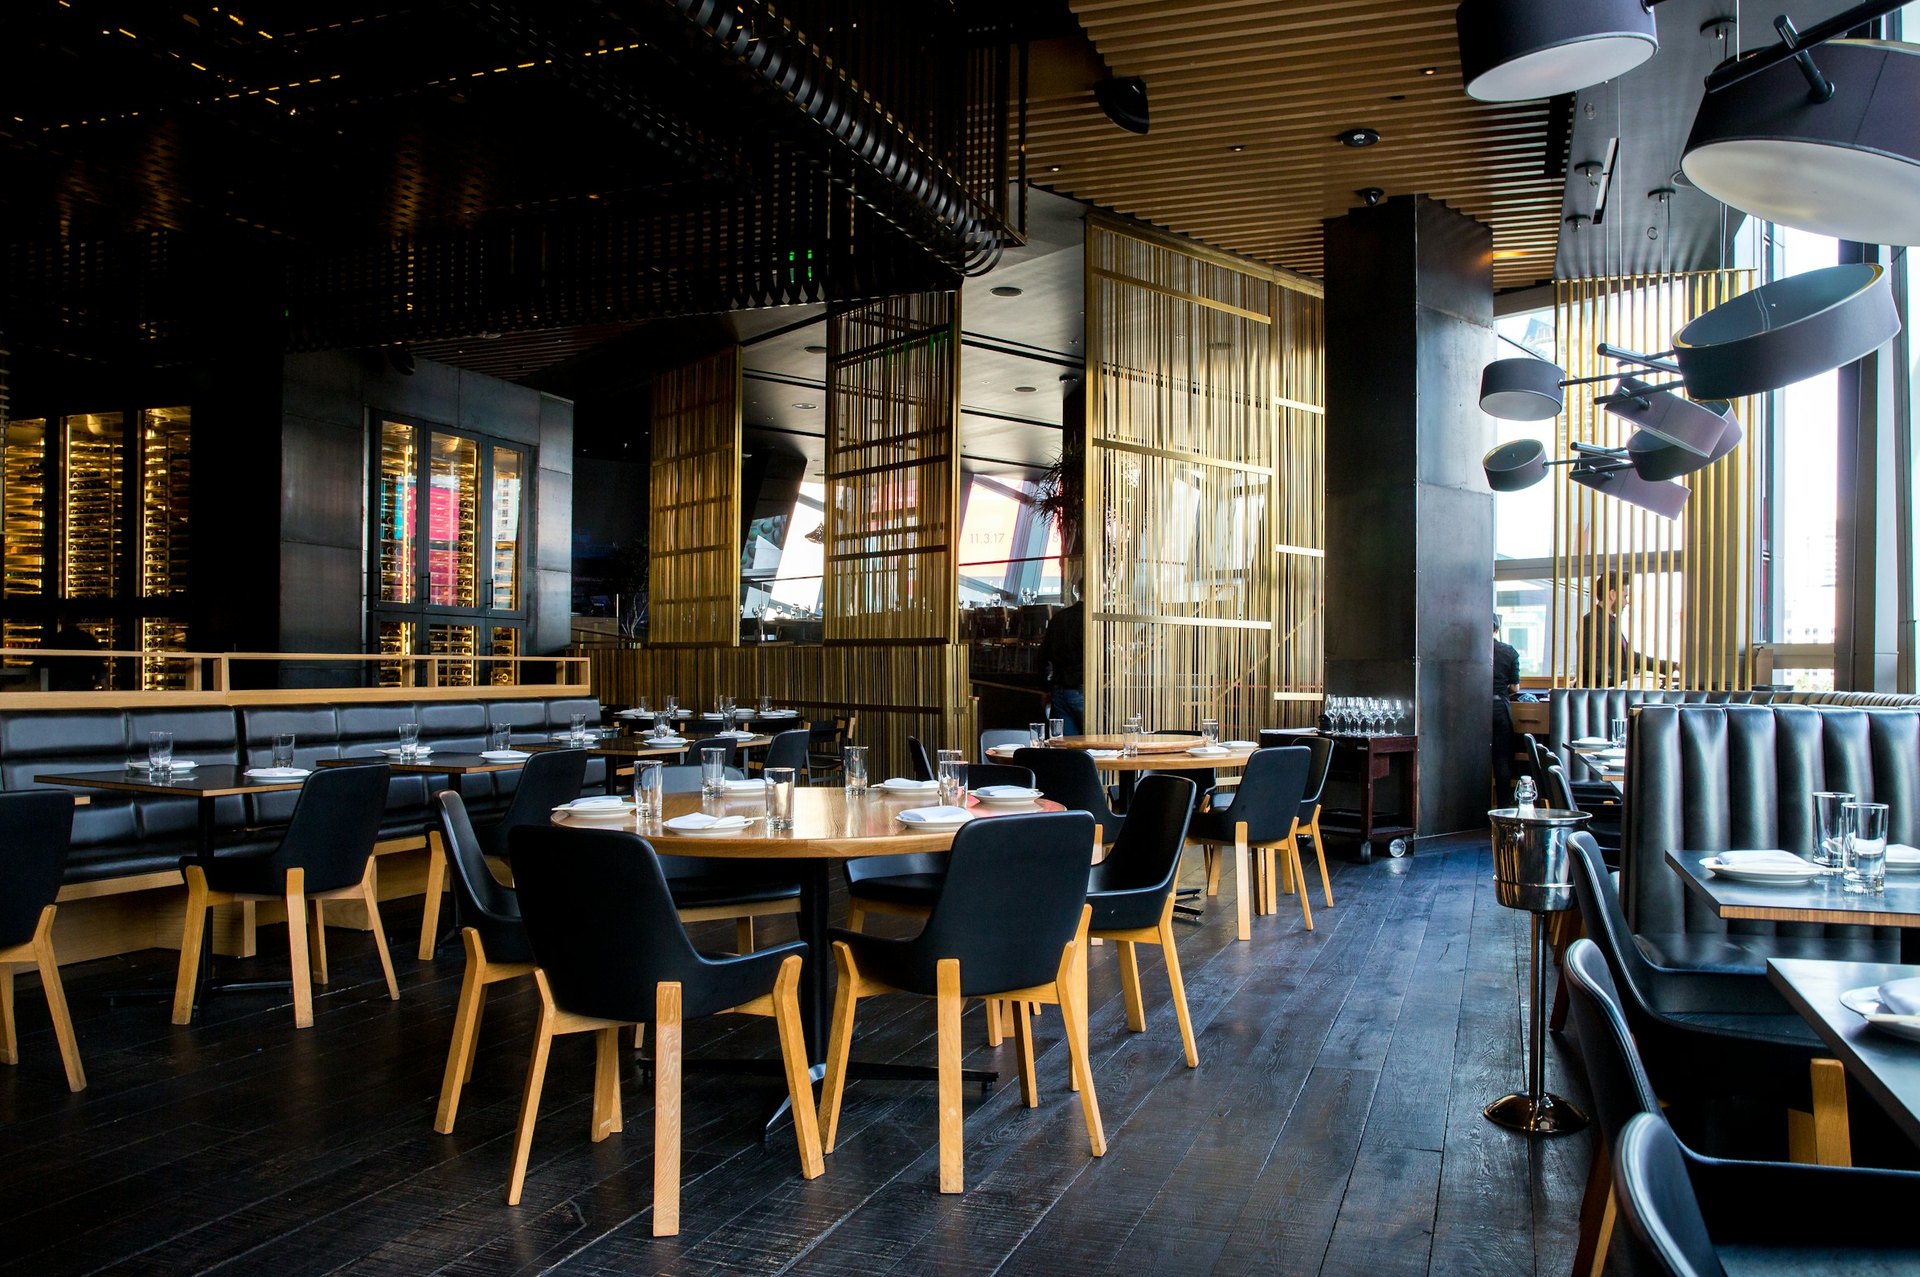
A $1,100,000 restaurant placed in service in April 2026, studied for the 2026 tax year.
Without a study, the owner would depreciate the full cost basis as 39 year property. Our engineers identified 31% of it as 5 and 15 year property. With 100% bonus depreciation, that $341,000 was deducted in the first year, and at a 37% tax rate it added $126,170 to the owner’s cash flow in year one.
- Property type
- Restaurant
- Cost basis
- $1,100,000
- Placed in service
- April 2026
- Tax rate
- 37%
- Bonus depreciation
- 100%
- $341,000
Accelerated depreciation, deducted in year one
- $126,170
Additional cash flow in year one at a 37% tax rate
- $28,205
Year-one deduction without a study, straight-line over 39 years
- $360,462
Year-one deduction with the study, more than 12 times as much
Where the $1,100,000 Went
- 5 year property$242,00022%
Kitchen equipment, counters, specialty electrical and dining room finishes
- 15 year property$99,0009%
Paving, signage, sidewalks, landscaping and drive-through features
- 39 year property$759,00069%
The shell, roof and structure, left on the standard schedule
Year-one figures are simplified: straight-line divides the basis evenly over 39 years and leaves out the mid-month convention. Results depend on your property.
Cost Segregation Results by Property Type
Accelerated depreciation is the part of the price our engineers moved onto 5, 7 and 15 year schedules. Select a study to see its full numbers.
- Property
- Short-term rental
- Year
- 2026
- Cost basis
- $1,100,000
- Accelerated depreciation
- $330,000
- Share
- 30%
- Property
- Office building
- Year
- 2026
- Cost basis
- $1,400,000
- Accelerated depreciation
- $364,000
- Share
- 26%
- Property
- Retail shopping center
- Year
- 2026
- Cost basis
- $2,000,000
- Accelerated depreciation
- $580,000
- Share
- 29%
- Property
- Restaurant
- Year
- 2026
- Cost basis
- $1,100,000
- Accelerated depreciation
- $341,000
- Share
- 31%
- Property
- Industrial warehouse
- Year
- 2026
- Cost basis
- $1,800,000
- Accelerated depreciation
- $360,000
- Share
- 20%
- Property
- Medical office
- Year
- 2026
- Cost basis
- $2,400,000
- Accelerated depreciation
- $792,000
- Share
- 33%
- Property
- Hotel
- Year
- 2026
- Cost basis
- $4,200,000
- Accelerated depreciation
- $1,344,000
- Share
- 32%